Finding the Best Retirement Planning Services in Charlotte NC
Find a trusted retirement planner in Charlotte NC for tax-smart strategies, cost-of-living planning, and fiduciary guidance. Start your free assessment today.


Find a trusted retirement planner in Charlotte NC for tax-smart strategies, cost-of-living planning, and fiduciary guidance. Start your free assessment today.
Start with three checks: Verify the planner's credentials, ask whether they act as a fiduciary, and get their fees in writing. Then ask how they would turn your savings, workplace benefits, taxes, and future healthcare costs into one retirement plan.
A good fit should make decisions easier, not give you another project to manage. I'm Evan Luongo, and I'll walk you through what to compare before you hire a retirement planner in Charlotte, NC.
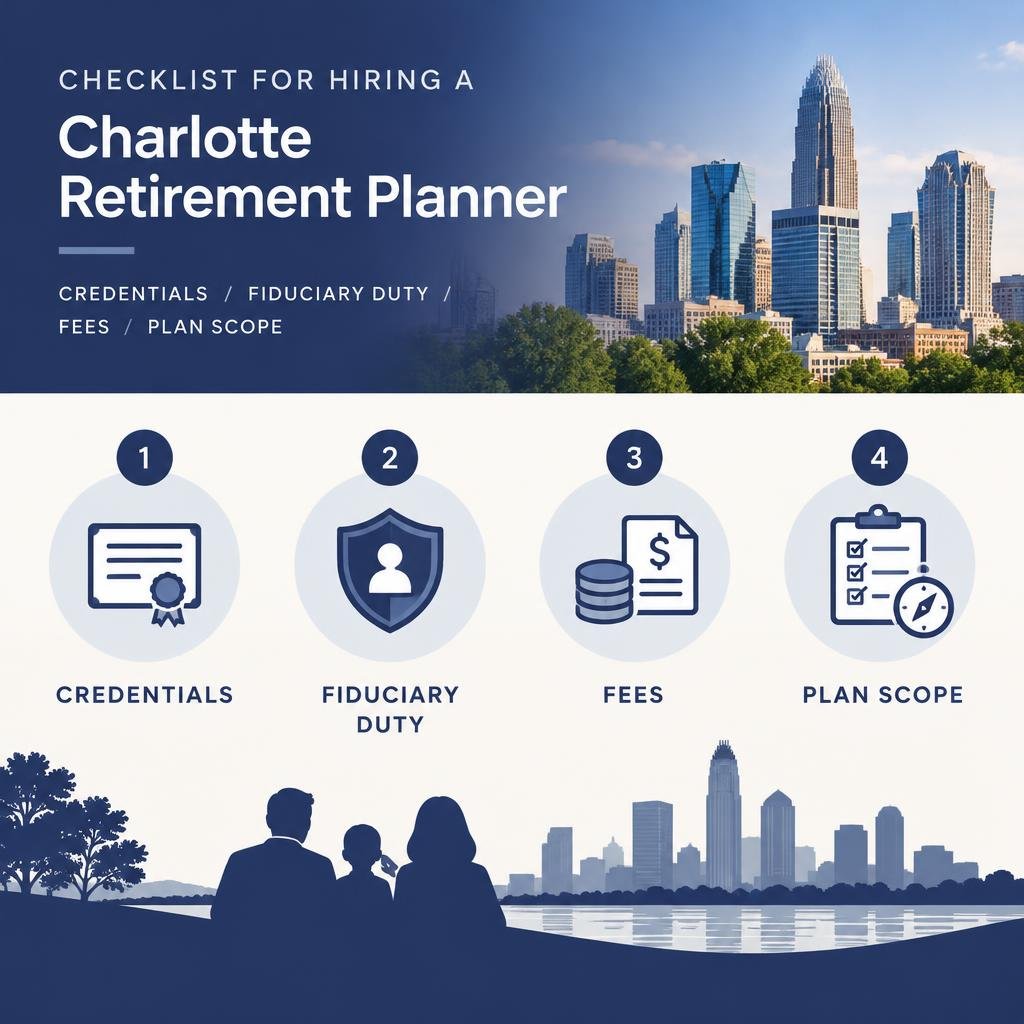
To build a comprehensive strategy, learn how a fiduciary financial advisor in Charlotte, NC operates, consult with a qualified financial advisor in Charlotte, NC, or partner with a dedicated wealth manager in Charlotte, NC.
The Queen City has quickly evolved into one of the most attractive retirement destinations in the Southeast. Consistently ranked among the top places to retire nationwide by U.S. News & World Report, Charlotte offers a balanced mix of urban vitality, mild seasonal weather, and an appealing tax structure. However, achieving lasting financial freedom requires navigating local property costs, state tax nuances, and complex healthcare considerations. According to the U.S. Bureau of Labor Statistics, the Charlotte-Concord-Gastonia metro area's consumer price index has continued to reflect steady cost-of-living growth, making local planning assumptions especially important for retirees.
Partnering with an advisor requires thorough vetting. You are not simply hiring someone to pick stocks; you are trusting them with the lifestyle you worked decades to build. With the number of Certified Financial Planner (CFP®) professionals in Charlotte growing steadily in recent years, you have plenty of options. The key is filtering out the noise to find high-caliber advice.
The most critical distinction when selecting a partner is whether they operate under a strict fiduciary standard. A true fiduciary is legally obligated to act in your best interests at all times. In contrast, non-fiduciary brokers or insurance agents may only be held to a "suitability" standard, allowing them to recommend financial products that pay them higher commissions even if a lower-cost, superior alternative exists.
When reviewing potential advisors, consult our fiduciary advisor Charlotte guide 2026 to see why designations like the CFP® credential matter. Working with a dedicated professional ensures your portfolio is free from third-party incentives and proprietary product quotas.
Financial advisory fees should never be a mystery. The two primary compensation models are fee-only and commission-based. We strongly advocate for fee-only compensation because it removes conflicts of interest entirely. In a fee-only structure, the firm charges a transparent percentage of assets under management, a flat retainer, or an hourly rate, taking zero compensation from mutual fund companies, insurers, or brokerage platforms.
To understand how straightforward pricing works, review our services and fees.
| Feature | Fee-Only Advisory Model | Commission-Based / Brokerage Model |
|---|---|---|
| Legal Duty | 100% Fiduciary Standard at all times | Suitability Standard (or dual-hatted) |
| Compensation Source | Directly from the client only | Commissions from product vendors and funds |
| Third-Party Incentives | None | Loads, 12b-1 fees, insurance commissions |
| Transparency | Clear dollar or percentage fee breakdown | Often buried in product expense ratios |
| Advice Objectivity | Unbiased and product-agnostic | Often skewed toward high-commission products |
Retirement wealth management is not just about asset accumulation; it is about wealth preservation, distribution planning, and risk management. As you transition out of your peak earning years, your portfolio must generate sustainable, tax-aware income while shielding you from prolonged market drawdowns.
While Charlotte remains relatively affordable compared to northeastern or West Coast metros, local inflation, particularly in housing, property taxes, and regional utilities, can quietly erode purchasing power over a 30-year retirement.
When mapping out your golden years, our guide on how to retire early without worrying about inflation eating your cash flow details how to maintain real purchasing power through inflation-protected securities, dividend-growth strategies, and dynamic spending adjustments.
The Financial Independence, Retire Early (FIRE) movement has gained massive traction across North Carolina, especially among professionals in tech, healthcare, and finance. However, retiring in your 40s or 50s introduces distinct risks, including a longer drawdown horizon and bridging health insurance before Medicare kicks in at age 65.
As we explore in can i retire early having enough money is only half the answer, early retirement demands precise modeling for longevity risk, sequence of returns, and bridge-account funding. Collaborating with an experienced wealth manager charlotte nc gives you the analytical framework to pull the trigger with complete confidence.

Tax management is one of the most reliable ways to preserve your retirement assets. North Carolina offers several attractive policies for retirees, but without proactive planning, unexpected tax liabilities can diminish your estate.
North Carolina ranks among the more tax-friendly states for retirees, according to Kiplinger's annual state-by-state retiree tax analysis. Key state tax policies include:
Sound estate planning guarantees your assets pass efficiently to your heirs without getting bogged down in the Mecklenburg County probate court system.
Integrating wills, healthcare directives, and revocable living trusts into your overall plan is essential. As detailed in our overview of estate planning for retirement, structuring your estate early also protects your family from the skyrocketing costs of long-term care and helps coordinate Medicare supplemental policies with private savings.
Even experienced professionals make critical financial missteps when entering retirement. Identifying these pitfalls early keeps your long-term plan on course.
The biggest operational shift in retirement is moving from accumulating assets to distributing them. Selling the wrong assets during a market downturn can cause irreparable damage to your portfolio through sequence-of-returns risk.
Establishing a structured retirement cash flow protocol safeguards your everyday liquidity. By applying our retirement cash flow model guide 2026, you can establish dynamic spending guardrails and a multi-tiered cash reserve, ensuring you never have to sell equities at a loss during temporary market pullbacks.
Charlotte is the second-largest financial hub in the United States, home to major corporate operations across banking, energy, and logistics. Many local executives hold complex packages comprising Restricted Stock Units (RSUs), non-qualified stock options, and deferred compensation plans.
Failing to diversify concentrated company stock or mismanaging the timing of deferred compensation payouts can trigger massive tax bills. Working with a dedicated financial advisor in charlotte nc allows corporate professionals to optimize their 401(k) contributions, coordinate equity vesting schedules, and harvest gains without unnecessary tax drag.
A comfortable retirement in the Charlotte metropolitan area typically requires an annual income between $65,000 and $110,000, depending on housing status and lifestyle preferences. Using the standard 4% withdrawal guideline, this translates to an investment portfolio between $1,000,000 and $2,000,000, alongside supplemental income sources like Social Security or corporate pensions.
No. North Carolina does not tax Social Security retirement benefits at the state level. However, depending on your total provisional income, up to 85% of your Social Security benefits may still be subject to federal income taxation.
A fee-only planner is compensated exclusively by the client through transparent, agreed-upon fees (hourly, flat, or a percentage of managed assets) and accepts no third-party sales commissions. A commission-based advisor earns revenue by selling specific financial products, insurance policies, or mutual funds, which can introduce conflicting incentives into their recommendations.
Building a dependable retirement strategy requires more than generic investment tips. It calls for an integrated roadmap combining disciplined investment management, tactical tax planning, healthcare budgeting, and legacy structuring tailored directly to the Charlotte economic landscape.
NoDa Wealth provides fee-only, fiduciary financial planning and wealth management for professionals and retirees. NoDa Wealth's transparent, data-driven approach removes sales pitches and commissions, using a clear 3-step process to give you complete clarity over your financial future.
Take the next step toward lifelong security. Visit NoDa Wealth's free assessment page to evaluate your retirement readiness today.
Educational Purposes Only. Content on this blog is for general educational and informational purposes only. It is not investment, tax, accounting, or legal advice, and it is not a recommendation or solicitation to buy or sell any security or to adopt any investment strategy. Past performance does not guarantee future results. Investing involves risk, including the possible loss of principal.
NoDa Wealth Management, LLC ("NoDa Wealth") is an investment adviser registered with the State of North Carolina. Advisory services are offered only where NoDa Wealth and its representatives are properly registered or exempt from registration. Readers should consult their own financial, tax, and legal advisors regarding their specific situation before making any decisions. For important disclosures, see the site footer and Form ADV.
Feeling overwhelmed? Let’s simplify things! Schedule your Free Assessment for an easy, 30-minute chat to help you tackle life’s transitions.
Enjoy a hassle-free conversation that puts your needs front and center!
)%20(3).avif)
